You don’t have to sell a parent’s house to pay for their care in California, and sometimes you shouldn’t. Selling makes sense when care is private-pay and no one will live in the home. When Medi-Cal will pay for a nursing home, keeping the house with an elder law attorney’s help can protect more of what your parent owns.
The short version
- In CareScout’s 2025 survey, California long-term care cost a median of $7,000 a month for assisted living and $12,167 a month for a shared nursing home room.
- A parent’s home does not count toward Medi-Cal’s $130,000 asset limit, but cash from selling it does, unless it buys another home within six months.
- Since 2017, California Medi-Cal estate recovery reaches only assets that pass through probate, so a house held in a living trust is generally out of reach.
- Selling a parent’s house requires legal authority, which means the parent’s own signature, a power of attorney covering real estate, a successor trustee, or a court-approved conservator.
- Time a parent spends in a licensed care facility can still count toward the IRS rule that excludes up to $250,000 of home-sale profit from federal tax.
Most of the families we talk to never planned on selling Mom or Dad’s house. It usually starts with a fall or a hospital stay, then a care facility, then a monthly invoice bigger than most mortgages, and meanwhile the house is sitting there with the porch light on a timer and nobody sure who’s even allowed to sign anything.
This is one of the hardest decisions a family makes, especially since that house holds all of your parent’s memories and a lot of yours too.
But even though it’s emotional, the decision comes down to a handful of practical questions: what care costs, what Medi-Cal counts, who has the legal right to sell, and what the house is costing every month it sits. This guide takes each one in order, including the situations where selling is the wrong move.
How much does long-term care cost in California in 2026?
Long-term care in California costs well above the national median. In the CareScout 2025 Cost of Care Survey, the California median was $7,000 a month for assisted living, $12,167 a month for a semi-private nursing home room, and $15,178 a month for a private room, while in-home care at 44 hours a week came to $7,627 a month.
At those medians, a year in a shared nursing home room comes to about $146,000 and a year of assisted living comes to about $84,000. CareScout notes that California calls assisted living a residential care facility, so that’s the name you may see on contracts and state paperwork. Individual facilities can land well above or below these numbers, so ask each one for a written monthly rate before you build a budget around it.
Do you have to sell a parent’s house to pay for their care?
No, California families aren’t required to sell a parent’s house to pay for care, and for some families keeping it is the smarter choice. The house is one possible source of money among several, and most families end up combining a few of them.
The usual sources are your parent’s income and savings, a long-term care insurance policy if one exists, Medi-Cal for a parent who qualifies, rent from the house, and help from family. Selling tends to make the most sense when care is private-pay, your parent won’t be moving back home, and no one in the family needs or wants to live in the house.
A reverse mortgage comes up a lot in these conversations, and it usually stops working once a parent moves into care. HUD’s model note for its HECM reverse mortgage allows the loan to be called due when a borrower is away from the home for more than 12 consecutive months because of physical or mental illness and no other borrower lives there. If your parent already has one, the balance is paid from the sale proceeds at closing.
What happens to a parent’s house when they move into a nursing home?
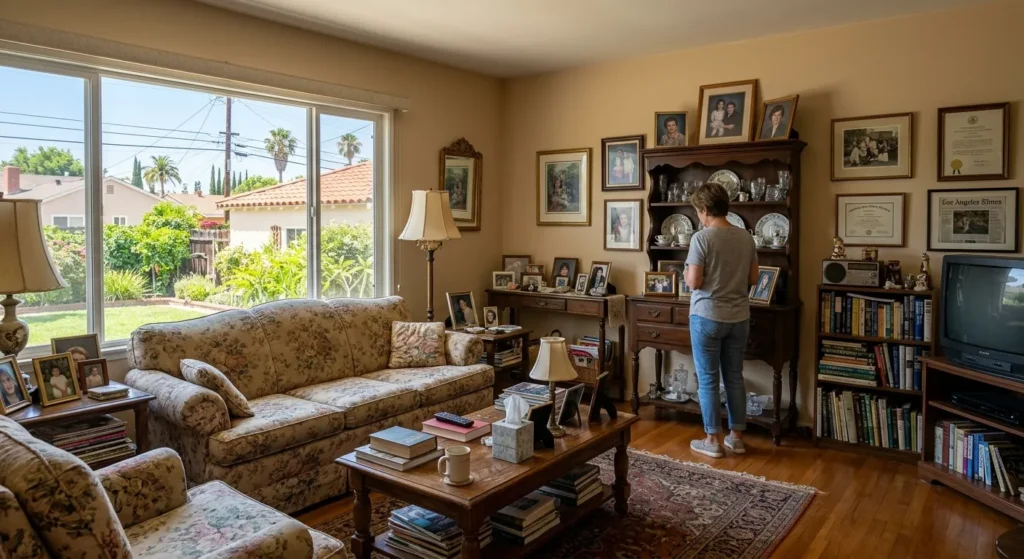
The house stays in your parent’s name, and every bill attached to it keeps coming. Property taxes, homeowner’s insurance, utilities, gardening, and repairs don’t stop because nobody is sleeping there, and an empty house in Los Angeles County carries its own risks, from break-ins to squatters.
Those costs depend on the neighborhood, the tax bill, and the condition of the house. In one Hawthorne house we bought, the family was spending more than $5,000 a month just to carry it. Add up your own number month by month before deciding whether holding the house for another year is worth it.
For Medi-Cal, the home generally stays exempt while your parent lives in a facility, as long as they intend to return home, according to the DHCS Medi-Cal property guide. Call the insurance company too and confirm the policy still covers the house while it’s empty, because a gap in coverage is the last thing a family needs on top of everything else.
Will selling the house hurt a parent’s Medi-Cal eligibility?
Selling can hurt Medi-Cal eligibility, because it turns an exempt asset into countable cash. This is the part of the decision we see families get backwards most often, and it’s worth slowing down for.
California brought back the Medi-Cal asset limit on January 1, 2026, at $130,000 for an individual, according to DHCS guidance on the reinstatement. Your parent’s home doesn’t count toward that limit. The money from selling it does count, unless it’s used to buy another home within six months, according to the DHCS property guide.
In real numbers, if the house sells and $400,000 lands in your parent’s account, they’re $270,000 over the limit, and they may not qualify for Medi-Cal until that money is spent down in ways Medi-Cal allows. At $12,167 a month in private-pay nursing care, that’s about 22 months. Medi-Cal also reviews transfers made on or after January 1, 2026, and giving money or property away for less than it’s worth can trigger a period of ineligibility.
None of this means selling is a mistake. When care is private-pay and Medi-Cal isn’t in the picture yet, selling can be exactly right. It means the timing and structure of the sale belong in front of an elder law attorney before anyone signs a listing agreement or a purchase contract. Our guide to selling a house to qualify for Medi-Cal goes deeper on this.
Can Medi-Cal take the house after a parent passes away?
Medi-Cal can only make a claim against the house if it goes through probate. For Medi-Cal members who died on or after January 1, 2017, the DHCS Estate Recovery Program limits repayment to assets in the probate estate, and only for nursing facility care, home and community-based services, and related hospital and prescription costs received at age 55 or older. If your parent owns nothing at death, nothing is owed.
In some cases the state can’t file a claim at all. According to the Los Angeles County DPSS estate recovery policy, there’s no recovery when the Medi-Cal member is survived by a spouse or registered domestic partner, a child under 21, or a child of any age who is blind or disabled, and DHCS can waive a claim that would cause substantial hardship. A hardship waiver has to be requested within 60 days of the date on the DHCS claim letter.
That’s why a living trust or another probate-avoidance plan, set up with an elder law attorney, can protect a house better than a rushed sale. Selling while your parent is alive takes the house out of the estate, but the cash can still end up in the probate estate if it’s in your parent’s name when they pass. For the full breakdown, read Can Medi-Cal Take Your House After Death in California? and Can a Nursing Home Take Your House in California?
Who has the legal right to sell a parent’s house in California?
Only someone with legal authority over the property can sign the sale, and who that is depends on how the house is titled and on your parent’s ability to make decisions. Start by pulling the grant deed or a title report so you know exactly whose name is on it.
If your parent is on title and still able to make decisions, your parent signs, and you can help with everything else. If they signed a durable power of attorney that gives the agent authority over real estate, the agent can sign on their behalf, and the title company will want to review that document early. If the house is in a living trust and your parent can no longer manage it, the successor trustee named in the trust can usually sell without going to court.
When a parent has dementia and never signed a power of attorney, the family usually needs a conservatorship of the estate through the Superior Court. Selling a conservatee’s home generally requires court authorization, and under California Probate Code section 2540 the conservator must tell the court whether your parent supports or opposes the sale and why alternatives like in-home care aren’t available. If your parent is in the early stages of memory loss, getting a power of attorney signed while they’re still able to sign it can spare the family that court process.
If your parent has already passed, the sale runs through the trust or through probate. Our guide to selling a house in probate in California covers that process, and Can You Sell a Parent’s House If They’re in Assisted Living? walks through the authority questions for a parent who’s still living.
Will your parent owe capital gains tax on the sale?
Often, no. Federal tax law lets a single homeowner exclude up to $250,000 of profit on the sale of a main home, or $500,000 for a married couple filing jointly, when they lived there at least two of the last five years, according to IRS Publication 523.
The rule that helps families in this situation is less well known. If your parent became physically or mentally unable to care for themselves and lived in the home for at least 12 months of the five years before the sale, the time they spend in a licensed care facility, like a nursing home, counts as time living in the house. That can keep the exclusion in place even after a long stay in care.
The math changes if the house is sold after your parent passes, and a house bought decades ago can carry a large gain either way, so ask a CPA to run your family’s numbers before you pick a closing date.
What if the house needs work or is full of belongings?
A house that needs work can still sell, and it doesn’t have to be fixed, cleaned, or emptied first. Plenty of homes that belonged to aging parents have original kitchens, older plumbing and electrical, a roof near the end of its life, and decades of belongings, and that’s normal for a house someone lived in for a long time.
You have three realistic paths. You can repair and update before listing, which usually brings the highest price and costs the most time and money up front. You can list it as-is with an agent, which saves the repair bill but can mean a longer wait and buyers who negotiate hard after inspections. Or you can sell as-is to a cash buyer, which usually means the lowest price of the three and the least work.
The move and the house also don’t have to be two separate projects. We worked with a family in Compton whose mother was moving into assisted living, and we drove her to her new place ourselves, coordinated the moving truck, and bought the house with everything she decided not to bring. The sale closed in 21 days, and her children got to spend that time getting her settled instead of emptying the house. If your parent’s move is coming up soon, ask any buyer you talk to whether they’ll help with the move and take the house with the leftover belongings, because not every buyer will.
Your options: list, sell for cash, rent, or keep the house
Every option below works for some California families and is the wrong call for others. The right one depends on your parent’s care plan, whether Medi-Cal is involved, the condition of the house, and how much time you have.
| Option | Works best when | Trade-offs |
| List with an agent | The house is in good condition and the family has time | A 5% to 6% commission ($40,000 to $48,000 on an $800,000 house), repairs, showings, and a longer timeline |
| Sell as-is for cash | Care bills are due now, the house needs work, or the family lives out of the area | A lower price than a retail sale, in exchange for no repairs, no showings, and a closing in as fast as 14 days |
| Rent the house out | Rent covers the care gap and someone local can manage the property | Landlord duties, repairs, California tenant laws, and rental income an elder law attorney should review for Medi-Cal |
| Keep it and plan with an elder law attorney | Medi-Cal will pay for nursing care and nobody needs cash from the house | Carrying costs continue, and the plan has to be set up correctly to keep the house out of probate |
| Reverse mortgage | Your parent still lives at home and plans to stay | The loan can be called due after 12 consecutive months away because of illness |
When a cash sale is the wrong choice
We buy houses for a living, and we’ll still tell you plainly when selling to a cash buyer doesn’t make sense. If the house is in good shape, your parent’s care is covered for the next several months, and the family can handle showings, listing with an agent will usually put more money in your parent’s pocket, even after the commission.
And if Medi-Cal will be paying for nursing care and nobody needs cash from the house, keeping it with an elder law attorney’s help may protect more of what your parent owns than any sale would.
A cash sale fits best when care bills are due now, the house needs work nobody can fund, or the family lives too far away to manage repairs, showings, and a cleanout. Mrs. Property Solutions is one of the buyers who purchases houses that need repairs as-is, and it’s one option on this list, not the only one.
Talk it through with a local buyer
If you’ve read this far, you’re probably still weighing it, and that’s okay, because this isn’t a decision anyone should rush.
Mrs. Property Solutions buys houses as-is across Los Angeles County and Southern California, and for families moving a parent into care, we can also help coordinate the move and handle everything left in the house after closing.
We’ve been doing this since 2016, we’ve purchased 150+ homes, and we have 50+ five-star reviews. We’re local to LA County, there are no repairs and no commissions, you choose the closing date, and the offer we make is the offer we honor.
If it would help to see a real number next to the other options in this guide, you can request a cash offer or call 626-344-9579. There’s no obligation to accept it.
Frequently Asked Questions
Can my parent just give me the house instead of selling it?
Sometimes, but never without an elder law attorney first. Medi-Cal’s transfer rules, the home’s exempt status, and the child’s future capital gains tax all depend on how and when the deed is signed. A gift that looks simple today can cost the family far more later, especially if your parent may need Medi-Cal nursing care.
Can we rent out Mom’s house to pay for her care?
Yes, renting works when the rent covers the gap in care costs and someone reliable can manage the property. It also makes the family a landlord, with repairs, tenant screening, and California tenant protection laws to follow. Ask an elder law attorney how rental income affects your parent’s Medi-Cal eligibility before signing a lease.
Can I sell my parent’s house if they have dementia and no power of attorney?
Yes, but usually only through a court-appointed conservatorship in California. A conservator of the estate generally needs court authorization to sell, and Probate Code section 2540 requires telling the court whether the parent supports the sale and why alternatives like in-home care won’t work. The court process takes time, so start early.
What happens to Medi-Cal if we sell our parent’s house?
The sale proceeds count toward Medi-Cal’s $130,000 asset limit for an individual, which returned on January 1, 2026. A parent over the limit can lose eligibility until the extra money is spent down in ways Medi-Cal allows, unless the proceeds buy another home within six months. An elder law attorney should plan this before the sale.
How fast can a parent’s house sell for cash in California?
A cash sale can close in as fast as 14 days in most transactions because there’s no lender approval or appraisal. Many families choose three to four weeks instead so the closing lines up with their parent’s move. The seller picks the date, and a conservatorship or probate can add time.
Is a cash offer on my parent’s house a lowball offer?
A cash offer is lower than a retail listing price because the buyer covers repairs, carrying costs, and resale. Mrs. Property Solutions shows how its number was reached. Compare offers by net proceeds, meaning what lands in your parent’s account after commissions, repairs, and months of carrying costs, not by the headline price.
Do we have to clean out Mom’s house before selling?
No. Families can take what they want and leave the rest, including furniture, clothes, and decades of belongings. When selling to Mrs. Property Solutions, the cleanout happens after closing with no out-of-pocket cost to the family. The cost of a large cleanout is built into the offer and explained before anyone signs.
Does the family pay fees or closing costs on a cash sale?
No, not in a standard Mrs. Property Solutions sale, where the seller pays no commissions and no standard closing costs. Existing liens, back property taxes, or a reverse mortgage balance are paid from the sale proceeds at closing, not out of pocket. Any exception is disclosed before signing, never introduced at the closing table.