You avoid probate in California by making sure a house is not titled in one person’s name alone at death. A funded living trust, a recorded transfer on death deed, or joint title each moves it to the next owner without a probate case. Each has a cost, and none prevents a property tax reassessment on its own.
TLDR
- A revocable living trust keeps a California house out of probate when the deed has been recorded in the trust’s name. A trust with no deed behind it generally does not.
- A California transfer on death deed is not effective unless it is recorded within 60 days of notarization. The law allowing it is set to end January 1, 2032, though deeds signed before then stay valid.
- Adding a child to a California deed can trigger a property tax reassessment, and survivorship overrides whatever the owner’s will says.
- The California small estate affidavit covers personal property up to $208,850 for deaths on or after April 1, 2025. It cannot transfer a house, which has its own court petition at $750,000 or less.
- Avoiding probate does not avoid a property tax reassessment, because Proposition 19 keeps the old taxable value only when a child makes the inherited family home their principal residence.
Probate is the court process that proves a will, settles a person’s debts, and hands what they owned to their heirs. It gets a worse reputation than it always deserves. For a family with clear paperwork and time to spare it can be slow but manageable, even though the delays and the fees are real.
What catches people off guard is that the title decides everything. Title is the record of who legally owns the house. When a house is titled in one person’s name and that person dies with no trust or deed in place, a court is the only route left for moving it to someone else. Every tool below settles that question early, while the owner is alive and able to sign.
If you are reading this because someone has already died, most of these tools are out of reach now, and that is hard to learn after the fact. The sections on the small estate affidavit and the primary residence petition cover what still works.
A house in one name goes through probate, and it is not cheap
A house titled in one person’s name alone, with no trust or transfer on death deed behind it, goes through probate in California.
The Orange County Superior Court puts the total cost of probate at 4% to 7% of the estate’s value, sometimes more. Under Probate Code section 10810, the estate’s attorney is paid 4% of the first $100,000, 3% of the next $100,000, and 2% of the next $800,000. Section 10800 sets the same schedule for the executor, the person who runs the estate.
On a house appraised at $900,000, that is $21,000 for the attorney and another $21,000 for the executor if the full fee is taken, before court costs and other expenses. The mortgage does not shrink the number, because the statute measures the estate without reference to what is owed.
A Burbank house that Mrs. Property Solutions bought from two sisters shows how this looks from the inside. Their father had died without a trust, so the estate went into probate. The house had sat untouched for years, with foundation problems and decades of belongings inside.
Both sisters lived out of state and worked with a probate attorney from a distance, and the sale closed in 21 days. They still went through a court process that a funded trust or a recorded transfer on death deed could have kept them out of.
The posts on what probate costs and how long probate takes cover both in detail.
A living trust works only if the house is in it
A revocable living trust keeps a California house out of probate when the house is titled in the trust’s name.
The owner creates the trust and usually serves as trustee, so nothing changes day to day. The owner also names a successor trustee, the person who takes over after death and hands the house to the beneficiaries. A revocable trust can be changed or canceled while the owner is alive.
The Orange County court’s guide notes that when a living trust holds title to property, the property passes to the beneficiaries without probate. The word that matters there is title. A trust document with no deed behind it holds nothing, so the house is still in the owner’s name and still goes to court.
A trust costs an attorney’s fee and some paperwork up front, and it does nothing about the property tax question covered further down.
A transfer on death deed has a 60-day rule and an end date
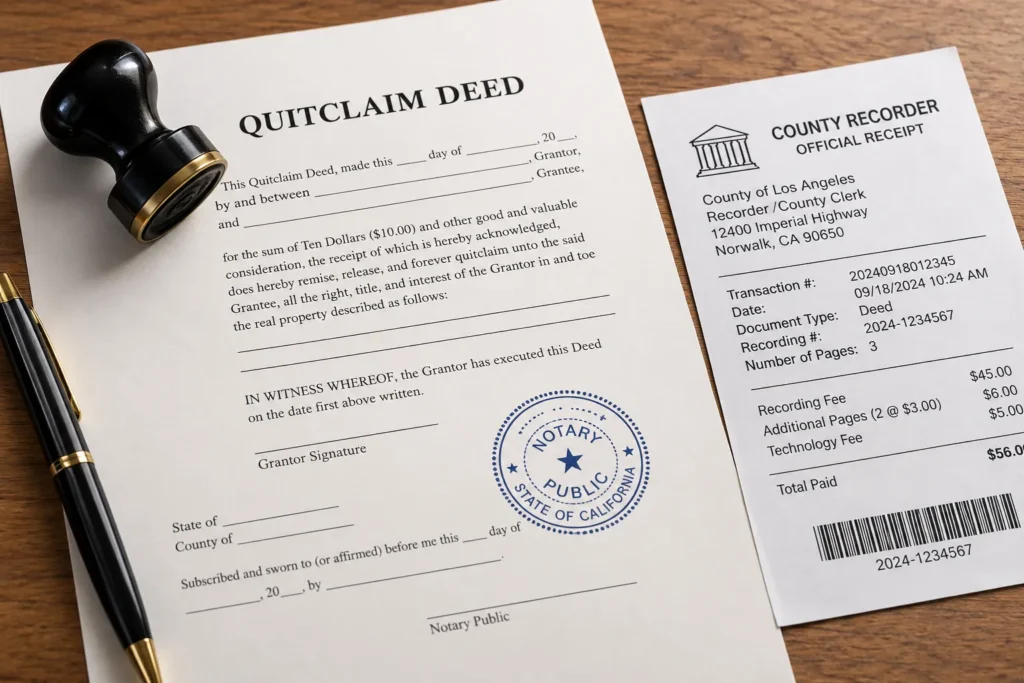
A revocable transfer on death deed, called a TOD deed, lets a California owner name who receives the house at death without a probate case.
The owner keeps the house and can cancel the deed at any time by recording a signed and notarized revocation. The transfer itself happens at death, not before. Under Probate Code section 5626, the deed has to be notarized and is not effective unless it is recorded within 60 days of the notarization date.
A signed deed sitting in a drawer does nothing.
The law that authorizes TOD deeds, Probate Code section 5600 and the sections after it, is scheduled to end on January 1, 2032 unless the Legislature extends it. Deeds signed before that date stay valid.
Adding a child to the deed is the shortcut that backfires
Adding a child to a California deed as a joint owner can avoid probate, but it comes with two catches.
The first catch is survivorship. When one joint owner dies, the surviving owner takes the property. The Orange County court’s guide notes that this overrides what the deceased owner’s will or trust says. A parent who adds one of three children to the deed and writes a will splitting the house three ways has, in practice, left the whole house to one child.
The second catch is property tax. The State Board of Equalization treats creating or transferring a joint tenancy interest as a change in ownership of the interest transferred, under Property Tax Rule 462.040. A change in ownership lets the county assessor reset that interest’s taxable value to current market value, which is called reassessment. Proposition 19 narrowed the parent-child exclusion, so a child who does not move into the house generally does not qualify, although the rule has exceptions.
Married couples often avoid this by holding title as community property with right of survivorship, which passes the house to the surviving spouse without probate. For anyone else, the court’s own guide says to talk to a lawyer before putting property in joint tenancy.
Beneficiary designations move the accounts, not the house
In California, retirement accounts, life insurance, and payable-on-death bank accounts pass to the person named without probate, according to the Orange County court’s guide. A payable-on-death account is one that names a beneficiary at the bank.
The name on file is who receives the money, so it is worth checking after a marriage, a divorce, or a death in the family.
The small estate affidavit cannot transfer a house
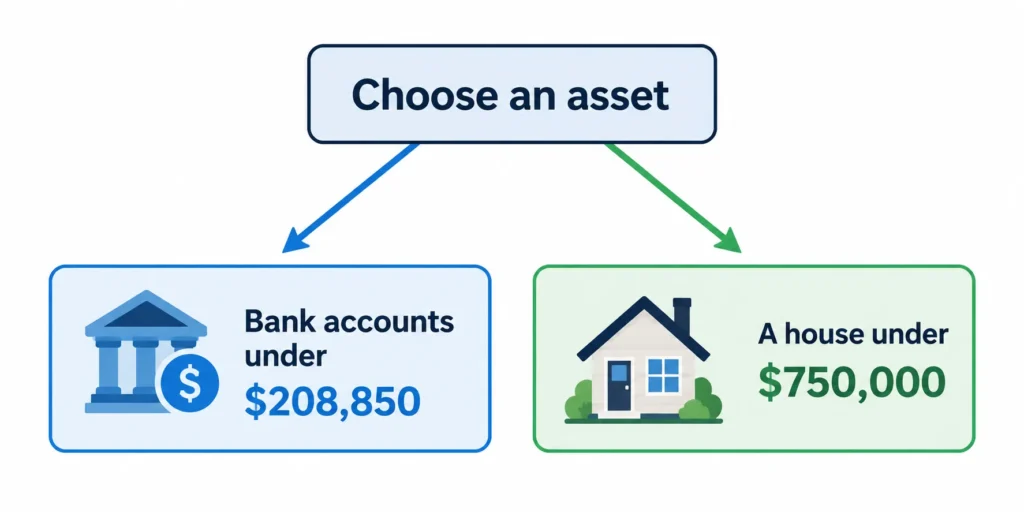
The California small estate affidavit collects personal property, such as bank accounts, and it cannot transfer a house.
An affidavit is a sworn written statement. This one lets a successor, the person entitled to inherit, collect a dead person’s property from a bank or other holder without a court case. The limit is $208,850 for anyone who died on or after April 1, 2025, according to the Judicial Council’s form DE-300. The next scheduled adjustment is April 1, 2028.
The limit counts the decedent’s California real estate too, with a few exceptions, so a family with a house and a bank account can be over the line before they start. The California Courts guide adds that at least 40 days must pass after the death and no probate case can have been opened.
A house follows a different route.
Under Probate Code section 13151, a successor can petition the superior court for a house that was the decedent’s primary residence in California. The house must have a gross value of $750,000 or less, and 40 days must have passed since the death. A court-appointed appraiser called a probate referee values the house, the petitioner notifies each heir within five business days of filing, and a judge signs an order. The limit was $184,500 for deaths before April 1, 2025, and the petition is still a court filing, not a paperwork-only fix.
Avoiding probate does not avoid a property tax reassessment
A trust or a TOD deed keeps a California house out of probate court, but it does not stop the county from reassessing the house.
The State Board of Equalization explains that a trust becomes a change in ownership when it turns irrevocable, meaning it can no longer be changed. That usually happens at the owner’s death.
Proposition 19 protects the parent’s old, lower taxable value only for a family home that was the parent’s principal residence and becomes the child’s principal residence. The child has to file for the homeowners’ exemption within one year of the death. The exclusion claim, form BOE-19-P, is due within three years or before the house is sold, whichever comes first.
There is also a cap. For transfers between February 16, 2025 and February 15, 2027, the exclusion covers the parent’s taxable value plus $1,044,586. Any market value above that amount is added to the taxable value. Say a parent’s home has a taxable value of $300,000 and is worth $1,500,000 at death. Then $155,414 sits above the cap, and the new taxable value is $455,414 instead of $1,500,000.
Rental homes do not qualify, and neither does any house that was not the parent’s principal residence. If the child later moves out, the house gets a new taxable value based on what it was worth when it was inherited.
If the death has already happened
If a California house is already in probate, the paths are keeping it, listing it with an agent, or selling it for cash, and each suits a different family. A cash sale is the wrong choice for a family that wants to keep the house or has months to spare on a house in good shape, and the full probate sale guide covers when each path fits.
After reading through the options, you may have found that most are closed to your family now, and that is a hard place to land. Mrs. Property Solutions buys probate houses and inherited houses across Los Angeles County in their current condition.
We work with the family’s probate attorney, so nobody has to manage repairs, showings, or a cleanout from a distance. Since 2016 we have purchased 150+ homes and earned 50+ five-star reviews from sellers, and we are local to LA County. There are no repairs and no commissions, and the offer we make is the offer we honor.
You can read how a probate sale works with us or call (626) 344-9579, and there is no obligation either way.
Frequently Asked Questions
Does a will avoid probate in California?
No. Probate is the California court process that validates a will and appoints an executor, so leaving a house by will alone does not avoid it. A house passes without probate only through a trust that holds title, a recorded transfer on death deed, joint ownership with survivorship, or a small estate procedure.
What is the small estate limit in California?
$208,850 is the small estate affidavit limit for anyone who died on or after April 1, 2025, according to Judicial Council form DE-300. The next scheduled adjustment is April 1, 2028. The affidavit collects personal property such as bank accounts, and it cannot transfer a house.
Can a house be transferred without probate if it is worth less than $750,000?
Yes, in some cases. Under Probate Code section 13151, a successor can petition the superior court for a decedent’s California primary residence worth $750,000 or less in gross value. Forty days must pass after the death. A probate referee appraises the house, and a judge still signs an order.
Does a living trust avoid probate if the house was never deeded into it?
Generally no. A trust avoids probate only for property it holds title to. A house still titled in the owner’s name goes through probate in California even when a trust exists, so the deed must be recorded in the trust’s name.
Is the transfer on death deed still available in California?
Yes. California’s TOD deed statute, Probate Code section 5600 and the sections after it, stays in effect until January 1, 2032 unless the Legislature extends it. Deeds signed before then remain valid. Under section 5626, the deed is not effective unless it is recorded within 60 days of notarization.
Will my children pay higher property taxes if they inherit my house?
Yes, unless the Proposition 19 parent-child exclusion applies. The house must be the parent’s principal residence and become the child’s. The child must also file for the homeowners’ exemption within one year, according to the California State Board of Equalization. Rental homes do not qualify.
Disclaimer: This article explains how avoiding probate generally works in California. It isn’t legal or tax advice, and rules vary by county and by situation. Talk to an estate planning or probate attorney about your specific case, and to a CPA or your county assessor about property taxes.
Helpful Resources
- Inherited a house in California
- Can You Sell a House Before Probate Is Completed in California?
- What Happens if a House Is in Probate With Debt in California?